| Mint (Digital) |
A free, automated tool aggregating transactions, categorizing spending, and providing budget alerts. |
- Real-time sync with bank accounts reduces manual entry.
- Customizable categories and goal tracking.
- Free for basic use, with optional premium features.
|
- Privacy concerns due to data aggregation.
- Limited advanced features for complex financial planning.
- Discontinued in 2024, though alternatives exist (e.g., YNAB, Personal Capital).
|
- Salaried
Income Optimization: Maximizing Earnings Within Constraints
Optimizing income involves strategic adjustments to both active and passive revenue streams while minimizing unnecessary expenditures. This section explores low-investment methods to generate additional income, audit recurring expenses for cost reductions, and align spending with variable earnings. By leveraging existing resources—such as skills, assets, or underutilized benefits—individuals can enhance financial resilience without compromising long-term stability.Effective income optimization requires a systematic approach to identifying overlooked opportunities and negotiating terms that improve cash flow. Below, structured strategies address passive income generation, expense renegotiation, and proactive financial alignment with income fluctuations.
Strategies for Generating Passive or Side Income with Minimal Upfront Investment
Low-barrier income streams can complement primary earnings without requiring significant capital or time commitments. These methods often rely on repurposing existing skills, assets, or digital platforms to create scalable revenue.
-
Gig Economy Platforms
Monetize underutilized time through flexible gigs such as:- Freelance services (e.g., writing, graphic design, virtual assistance) via platforms like Upwork or Fiverr.
- Delivery or task-based work (e.g., food delivery, errands) through apps like DoorDash or TaskRabbit.
- Rideshare or courier services (e.g., Uber, Lyft, Amazon Flex) during off-peak hours.
Example: A professional with 5 hours/week of spare time could earn $200–$500/month by offering editing services on Fiverr, with no additional costs beyond time.
-
Monetizing Hobbies or Niche Skills
Convert personal interests into revenue through:- Digital products (e.g., e-books, templates, or printables) sold on Etsy or Gumroad.
- Online courses or tutorials (e.g., teaching a language, cooking, or coding) via Udemy or Teachable.
- Affiliate marketing by promoting products (e.g., Amazon Associates) through blogs or social media.
Key Insight: Platforms like Patreon allow creators to earn $50–$200/month from as few as 100 dedicated supporters by offering exclusive content.
-
Leveraging Existing Assets
Generate income from idle resources:- Renting out storage space (e.g., Neighbor, Stowga) or parking spots (e.g., SpotHero).
- Monetizing unused vehicles (e.g., Turo for car rentals or Getaround for peer-to-peer sharing).
- Selling unused items (e.g., clothing, electronics) on Poshmark, eBay, or Facebook Marketplace.
Data Point: The average U.S. household earns $1,000–$3,000/year by renting out a spare room or parking space (Source: Neighbor, 2022).
-
Automated or Semi-Passive Income
Implement systems that generate revenue with minimal ongoing effort:- High-yield savings accounts or CDs (e.g., Ally, Marcus) for interest income.
- Dividend stocks or ETFs (e.g., SCHD, VYM) with low minimum investments.
- Peer-to-peer lending (e.g., Prosper, LendingClub) for fixed returns (typically 5–10% APY).
Caution: Prioritize liquidity and risk tolerance; semi-passive income often requires initial research or maintenance.
Audit and Renegotiation of Recurring Expenses
Recurring expenses—such as subscriptions, utilities, and memberships—often accumulate silently, eroding disposable income. A structured audit and renegotiation process can uncover savings of 10–30% on fixed costs.
-
Identifying Unused or Underutilized Subscriptions
Conduct a 30-day expense review to categorize subscriptions by:- Frequency of use (e.g., gym memberships, streaming services).
- Value derived (e.g., professional tools vs. redundant apps).
- Auto-renewal status (e.g., forgotten trials or lapsed promotions).
Example: The average U.S. consumer spends $230/year on unused subscriptions (Source: Credit Karma, 2023).
-
Script for Polite but Firm Renegotiation
Use a standardized template to request discounts or cancellations:
"I’ve been a loyal customer for [X years/months] and appreciate the service. Given my [usage level/family size], I’d like to discuss reducing my monthly fee to [$X] or explore a more cost-effective plan. Could you share options or promotions available to long-term customers?"
Tactics for Success:- Call during off-peak hours (e.g., early mornings or weekends) when agents have more flexibility.
- Mention competitors’ offers (e.g., "I noticed [Competitor] offers a similar plan for $Y—can you match this?").
- Bundle services (e.g., internet + TV) for volume discounts.
-
Negotiating Bills with Service Providers
Target high-impact bills (e.g., internet, insurance, phone plans) using:- Internet/TV: Threaten to switch to a competitor unless a $10–$30/month reduction is granted.
- Insurance: Request a loyalty discount after 1–2 years of claims-free service.
- Phone Plans: Downgrade data tiers or switch to prepaid options (e.g., Mint Mobile offers $15–$30/month for unlimited talk/text).
Real-World Example: A family in Texas saved $50/month by negotiating their internet bill from $80 to $30 after citing a competitor’s promotional rate.
-
Automating Expense Tracking
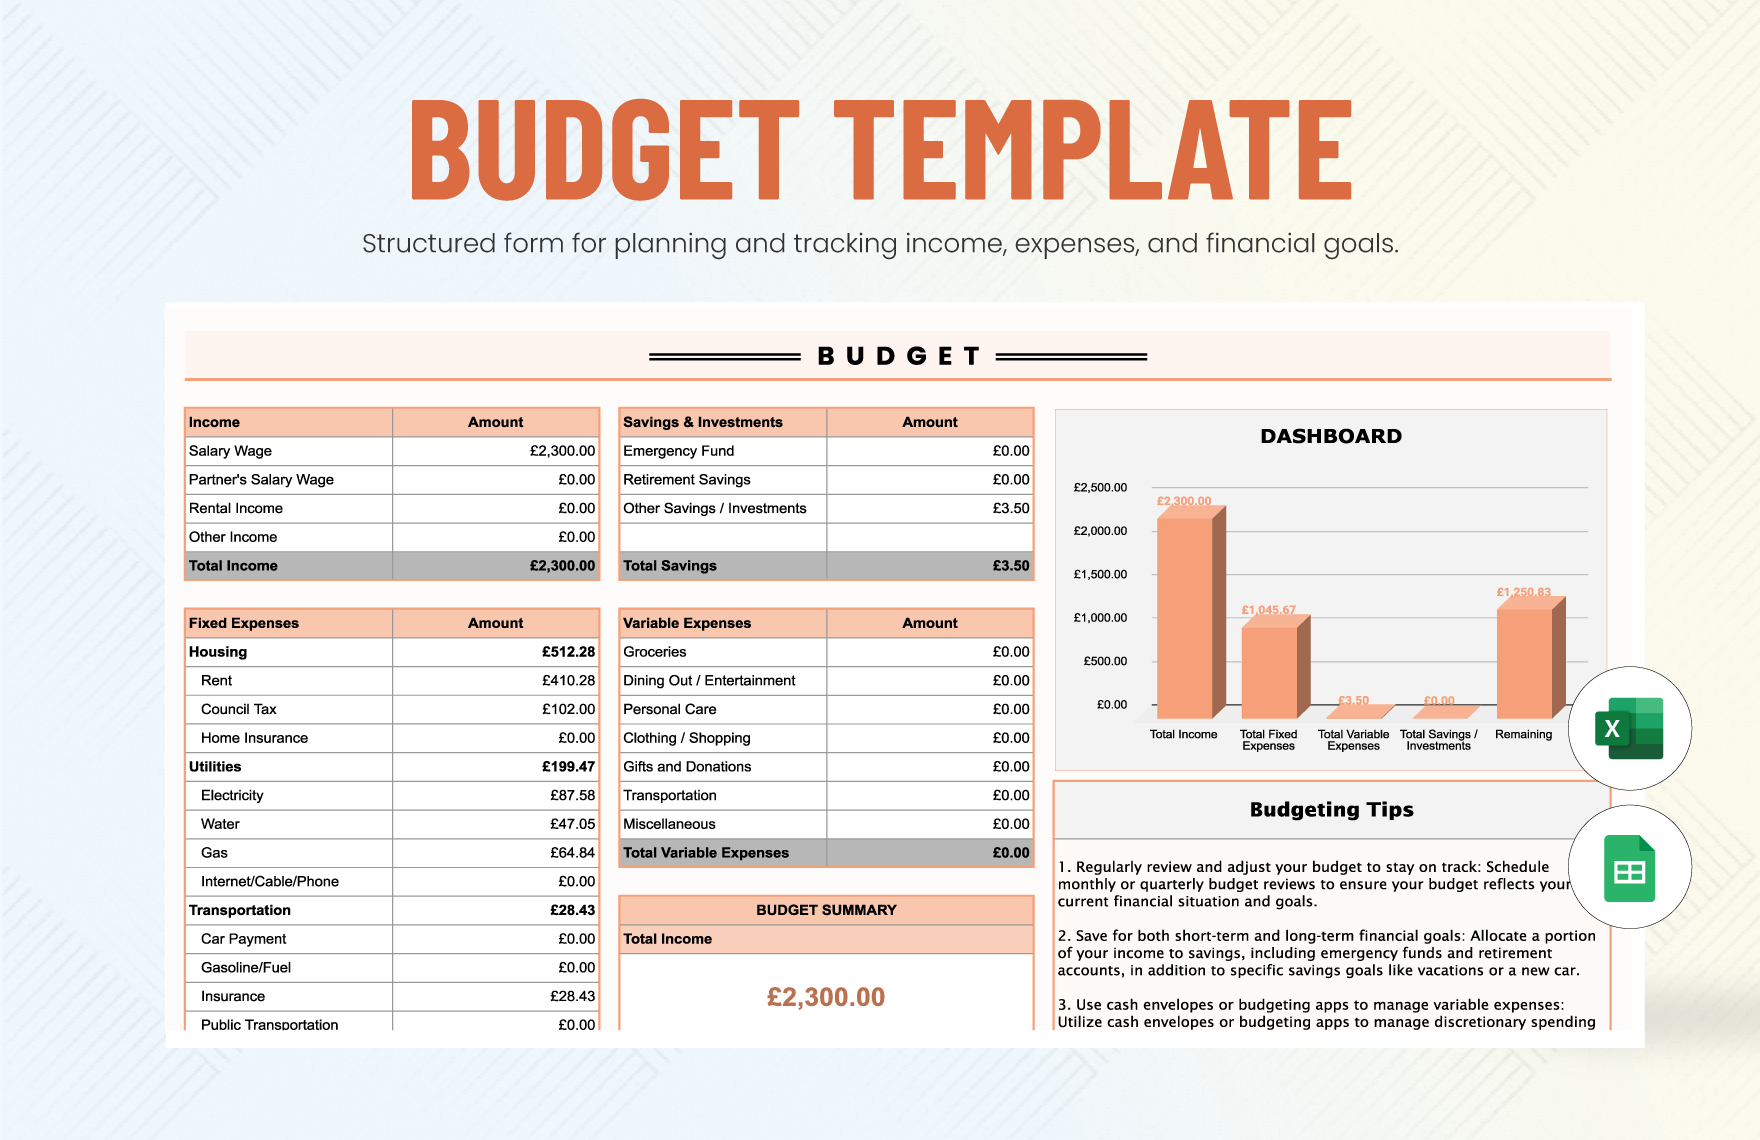
Use tools like Mint, YNAB, or Personal Capital to:- Flag duplicate or forgotten subscriptions.
- Set alerts for bill due dates to avoid late fees.
- Compare historical spending to identify seasonal trends (e.g., holiday subscriptions).
Checklist for Identifying Untapped Income Streams
Overlooked financial opportunities often lie in tax benefits, employer perks, or forgotten assets. A systematic checklist ensures no potential revenue source is missed.
-
Tax Refunds and Credits
- Review prior tax returns for missed credits (e.g., Earned Income Tax Credit, Saver’s Credit).
- Adjust withholding allowances to avoid overpaying quarterly taxes.
- File amended returns for prior years if eligible (e.g., $1,000+ in missed deductions).
Statistic: The IRS reports $1.3 billion in unclaimed refunds annually due to missed credits (Source: IRS, 2022).
-
Employer Benefits and Perks
- Utilize Flexible Spending Accounts (FSAs) or Health Savings Accounts (HSAs) for tax-free spending on medical/dental expenses.
- Negotiate remote work stipends or tuition reimbursement programs (e.g., $5,250/year tax-free under IRS Section 127).
- Check for unused vacation days or profit-sharing bonuses (e.g., companies like Costco offer $6,000/year in profit-sharing).
-
Overlooked Assets and Liabilities
- Unused gift cards: Sell or transfer balances via platforms like CardCash or Raise.
- Old electronics/devices: Trade-in programs (e.g.,
Smart Spending: Prioritizing Needs vs. Wants with Data-Driven Decisions
Effective budgeting requires more than tracking income and expenses—it demands a structured approach to spending that aligns with financial goals, emotional well-being, and long-term value. Data-driven decision-making transforms spending from reactive to intentional, ensuring resources are allocated where they matter most. This section explores a categorized spending hierarchy, behavioral triggers that influence impulsive purchases, and actionable strategies to optimize discretionary spending without compromising quality of life.
Categorized Spending Hierarchy: Ranking Expenses by Urgency, Impact, and Value
A structured hierarchy clarifies spending priorities by evaluating three dimensions: urgency (immediate necessity), emotional impact (subjective fulfillment), and long-term value (future financial or lifestyle benefits). Below is a tiered framework with examples for each category, ranked from highest to lowest priority.Importance of the Hierarchy:
This model prevents overspending on low-value categories while ensuring essential needs are met. It also helps identify opportunities to reallocate funds from discretionary areas to high-impact investments (e.g., education, health, or retirement).
-
Tier 1: Non-Negotiable Needs
- Examples: Housing (mortgage/rent), utilities (electricity, water), groceries, transportation (public transit or car payments), minimum debt payments (student loans, medical bills), and insurance (health, auto, homeowners).
- Characteristics:
- Directly tied to survival, legal obligations, or basic functionality (e.g., electricity to avoid service disconnection).
- Emotional impact: High stress if unmet (e.g., late rent payment leading to eviction).
- Long-term value: Non-negotiable; cutting here risks severe consequences.
-
Tier 2: High-Impact Investments
- Examples: Retirement contributions (401(k), IRA), emergency savings, professional development (certifications, courses), preventive healthcare (dental cleanings, annual check-ups), and home maintenance (HVAC servicing, roof repairs).
- Characteristics:
- Not immediate needs but critical for long-term stability or growth. Delaying these may incur higher costs later (e.g., untreated dental issues leading to expensive procedures).
- Emotional impact: Mixed—short-term sacrifice for future security (e.g., skipping a vacation to fund a retirement account).
- Long-term value: Compound significantly over time (e.g., $200/month in a retirement account at 7% return grows to ~$250,000 in 30 years).
-
Tier 3: Quality-of-Life Enhancers
- Examples: Gym memberships, organic groceries, streaming services, hobby supplies (e.g., photography equipment), or family outings.
- Characteristics:
- Improve daily happiness or efficiency but are not essential. Often tied to personal values (e.g., a musician prioritizing instrument lessons over a new TV).
- Emotional impact: High subjective satisfaction but diminishing returns (e.g., adding a third streaming service may not double enjoyment).
- Long-term value: Depends on alignment with goals (e.g., language classes for career growth vs. impulse buys).
-
Tier 4: Discretionary Luxuries
- Examples: Dining out, designer clothing, concert tickets, non-essential subscriptions (e.g., niche apps), or impulse purchases (e.g., clearance-rack finds).
- Characteristics:
- Purely optional and often driven by external influences (social media, advertising).
- Emotional impact: Short-term dopamine spikes but may lead to guilt or financial strain.
- Long-term value: Minimal unless tied to a deliberate goal (e.g., a business networking event).
-
Tier 5: Low-Value Indulgences
- Examples: Vending machine snacks, last-minute takeout, unused memberships (e.g., gym fees for a lapsed account), or duplicate purchases (e.g., multiple phone chargers).
- Characteristics:
- Provide negligible benefit and are easily forgotten or wasted.
- Emotional impact: Temporary relief from boredom or stress.
- Long-term value: Negative (erodes savings or increases debt).
Key Insight: The hierarchy is fluid—what qualifies as a "need" for one household (e.g., a reliable car for rural commuters) may be a "want" for another. Adjust tiers based on personal circumstances, but prioritize Tier 1 and Tier 2 to build financial resilience.
Behavioral Triggers for Impulsive Spending and Countermeasures
Impulsive spending often stems from psychological triggers that bypass rational decision-making. Recognizing these patterns allows for proactive countermeasures to regain control over discretionary expenses.Common Behavioral Triggers: -
Emotional Distress
- Trigger: Stress, loneliness, or fatigue (e.g., retail therapy after a breakup or online shopping during layoffs).
- Countermeasures:
- Delay purchases by 24–48 hours to allow emotions to stabilize.
- Redirect spending to a "comfort fund" (e.g., a small savings account earmarked for emotional needs).
- Replace the habit with a non-financial activity (e.g., journaling, walking, or calling a friend).
-
Social Pressure
- Trigger: FOMO (fear of missing out), peer comparison, or cultural norms (e.g., keeping up with colleagues' vacations or gadgets).
- Countermeasures:
- Adopt a "30-day rule": Wait a month before committing to a socially driven purchase (e.g., a new phone released by a friend).
- Reframe spending as an investment in experiences over possessions (e.g., a group hike instead of a fancy restaurant).
- Use the "10/10/10 Rule" (Suzy Welch): Ask if the purchase will matter in 10 days, 10 months, or 10 years.
-
Convenience and Frictionless Transactions
- Trigger: One-click purchases, subscription aut renewals, or proximity to spending (e.g., impulse buys at checkout counters).
- Countermeasures:
- Enable two-factor authentication for online purchases to add friction.
- Unsubscribe from marketing emails and use apps like Unroll.me to manage subscriptions.
- Physically remove payment methods from high-risk platforms (e.g., save credit cards only for essentials).
-
Anchoring and Scarcity
- Trigger: Limited-time offers, "original price" comparisons, or exclusive deals (e.g., Black Friday sales or "only 3 left!" alerts).
- Countermeasures:
- Ignore sale emails until after the event; research whether the item is genuinely needed.
- Use price-tracking tools (e.g., CamelCamelCamel for Amazon) to verify if the "discount" is a true savings.
- Set a "price ceiling" for non-essential items (e.g., "I won’t pay more than
Saving Strategies: From Short-Term Goals to Long-Term Wealth
Effective saving strategies bridge immediate financial security with long-term wealth accumulation, requiring a tailored approach to liquidity, risk tolerance, and tax efficiency. High-yield savings accounts, certificates of deposit (CDs), and short-term bonds each serve distinct purposes, while automation and disciplined contribution methods mitigate behavioral barriers to saving. Understanding opportunity costs—such as sacrificing short-term gratification for future financial resilience—further clarifies the strategic allocation of resources. Below, comparative tools, step-by-step automation frameworks, and visual projections illustrate how compound interest and systematic saving transform modest contributions into substantial wealth over time.
Comparison of Short-Term Savings Instruments
The selection of a savings vehicle depends on interest rate returns, liquidity needs, and tax implications. Below is a side-by-side comparison of high-yield savings accounts (HYSA), certificates of deposit (CDs), and short-term bonds for U.S. and international savers, incorporating current (as of 2024) average rates, penalties, and tax treatments.
| Feature |
High-Yield Savings Account (HYSA) |
Certificates of Deposit (CDs) |
Short-Term Bonds (e.g., Treasury Bills, Corporate Notes) |
|---|
| Interest Rates (APY/APR) |
- U.S.: ~4.0–5.0% (variable, tied to Fed rates).
- International: ~2.5–4.5% (varies by region; e.g., EU ~2.0–3.5%).
|
- U.S.: 4.5–5.5% (fixed, 3–12 months); 5-year CDs ~4.2–4.8%.
- International: ~3.0–5.0% (e.g., UK ~4.5%, Canada ~5.0%).
|
- U.S. Treasury Bills (4-week to 1-year): ~5.0–5.3%.
- Corporate Commercial Paper (3–9 months): ~4.8–5.5%.
- International: ~3.5–5.0% (e.g., German Bunds ~2.5–3.0%).
|
| Liquidity |
- Unlimited withdrawals (6 transactions/month per U.S. Regulation D).
- No penalties for early access (though rates may vary).
|
- Penalties for early withdrawal (e.g., 3–6 months’ interest lost).
- Laddering CDs (rolling maturities) mitigates lock-in risk.
|
- Primary market: Held to maturity (e.g., 3–12 months).
- Secondary market: May trade at a premium/discount; call risk for corporate bonds.
|
| Tax Implications (U.S.) |
- Interest taxed as ordinary income (no deferral).
- FDIC-insured up to $250K per account.
|
- Same as HYSA; state/local taxes may apply.
- No tax advantages beyond standard interest treatment.
|
- U.S. Treasuries: Federal tax-exempt (state/local taxes may apply).
- Corporate bonds: Fully taxable (ordinary income).
- Municipal bonds (if applicable): Tax-free for residents of issuing state.
|
| Tax Implications (International) |
- Taxed per local laws (e.g., UK: ~20% savings tax; EU: ~15–30%).
- May require FATCA/CRS compliance for non-residents.
|
- Similar to HYSA; some jurisdictions offer tax-advantaged CDs (e.g., Singapore’s Supplementary Retirement Scheme).
|
- Bond interest taxed per issuer’s country (e.g., Eurobonds taxed in investor’s home country).
- Double taxation treaties may reduce withholding rates.
|
| Best Use Case |
Emergency funds, short-term goals (<1 year), frequent access. |
Strategic saving (1–5 years), higher yields than HYSA. |
Tax-efficient saving (U.S. Treasuries), institutional investors, or lock-in higher yields. |
- U.S. Savers: Prioritize HYSA for liquidity or CDs for slightly higher yields if funds are untouchable. Treasury bills offer tax advantages for high earners.
- International Savers: Assess local tax rates (e.g., UK’s Personal Savings Allowance) and currency risk (e.g., holding USD-denominated bonds in a weakening local currency).
- Risk Tolerance: Bonds carry minimal credit risk (for sovereign issuers) but may underperform inflation over time.
Automating Savings: Systematic Contributions and Behavioral Discipline
Automation removes emotional decision-making from saving, ensuring consistency regardless of income fluctuations. The "pay-yourself-first" principle—redirecting a portion of income to savings before discretionary spending—aligns with psychological triggers that favor immediate gratification. Below is a step-by-step guide to implementing automated saving strategies, including direct deposits, round-up apps, and employer deductions.Step 1: Set Clear Savings Goals with Time Horizons
Define short-term (0–1 year), medium-term (1–5 years), and long-term (5+ years) goals with associated target amounts. Example:
- Short-term: $5,000 emergency fund.
- Medium-term: $20,000 down payment for a home (3 years).
- Long-term: $500,000 retirement nest egg (20 years).
Step 2: Configure Direct Deposits to Savings Accounts
- U.S. Employers: Use Form W-4 to split direct deposits into checking and savings accounts (e.g., 10–20% to savings).
- International/Non-Employed: Set up automatic transfers via bank apps (e.g., Revolut, Wise) or third-party tools (e.g., Digit, Qapital).
- Example: Deposit $500/month into a HYSA on payday (adjustable based on income).
Step 3: Leverage Round-Up and Micro-Saving Apps
Round-up apps (e.g., Acorns, Chime) automatically transfer spare change from purchases to a savings account. Configure rules such as:
- Round up all transactions to the nearest dollar.
- Set a weekly/monthly cap (e.g., $50) to avoid over-saving for short-term goals.
- Example: $3.50 coffee → $4 charged, $0.50 saved.
Step 4: Utilize Employer-Driven Savings Plans
- 401(k)/403(b): Contribute pre-tax income (reduces taxable income by up to $23,000/year in 2024 for U.S. plans).
- Health Savings Accounts (HSAs): Triple tax-advantaged (pre-tax contributions, tax-free growth, tax-free withdrawals for medical expenses).
- Example: Allocate 15% of salary to a 40
Mastering budgeting is not about restriction but empowerment: the freedom to spend consciously, save aggressively, and future-proof financial well-being. This guide bridges theory and practice, offering frameworks for every income level and life stage—from freelancers balancing irregular earnings to retirees optimizing fixed incomes. By adopting even one strategy from these pages, individuals can reduce financial anxiety, capitalize on untapped income streams, and harness the power of compounding to turn modest savings into lasting prosperity. The ultimate budget is not a constraint; it is the foundation of a life designed by choice, not chance.
|
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of ir.msu.ac.zw.