| 50/30/20 Rule |
- 50% Needs (housing, food, utilities)
- 30% Wants (discretionary spending)
- 20% Savings/Debt Repayment
|
- Reallocate 5% of "Wants" (15% total) to a Fortune Fund (e.g., crypto, angel investing, or speculative assets).
- Dedicate 5% of "Savings" to skill-building (e.g., online courses, mentorship).
- Use windfall income (bonuses, tax refunds) to top up the Fortune Fund first.
|
- Simple and intuitive for beginners.
- Encourages balanced living without extreme austerity.
- Flexible enough to absorb cultural spending norms.
|
- Rigid 50/30/20 split may not suit high-income earners or those with variable expenses.
- Limited focus on asset growth beyond traditional savings.
|
- Individuals with stable incomes seeking a balanced approach to wealth-building.
- Cultures where discretionary spending is socially significant (e.g., leisure, social events).
|
| Zero-Based Budgeting |
- Every dollar is assigned a specific purpose (income – expenses – savings = $0).
- Prioritizes intentional spending and elimination of waste.
|
- Introduce a "Fortune Category" where 10–15% of income is earmarked for high-reward, low-probability opportunities (e.g., startups, real estate flips).
- Use monthly "luck audits" to reassess allocations based on new opportunities (e.g., a sudden side hustle income stream).
- Allocate 1% of income to "black swan" preparedness (e.g., cybersecurity tools, legal protections for speculative ventures).
|
- Highly customizable and precise.
- Encourages accountability and eliminates financial leaks.
- Ideal for high-earners or entrepreneurs with irregular income.
|
- Time-consuming to maintain.
- Requires disciplined tracking, which may deter some users.
- Less forgiving for unexpected expenses.
|
- Freelancers, small business owners, or high-income professionals with fluctuating cash flows.
- Individuals who thrive on data-driven decision-making.
|
| Pay-Yourself-First (PYF) with Fortune Multipliers |
- Automate savings/investments before discretionary spending.
- Typically
Strategic Allocation: Optimizing Funds for High-Reward, Low-Effort Fortune Potential
Budgeting for long-term prosperity requires more than mere restraint—it demands intentional allocation of resources toward opportunities that align with risk tolerance, market cycles, and external fortune-enhancing factors. While emergency funds and conservative savings form the foundation, fortune-driven individuals strategically reallocate discretionary and high-liquidity funds into assets capable of exponential growth with minimal active management. This tiered approach balances stability with speculative potential, ensuring that every dollar serves a purpose—whether through passive income streams, speculative assets, or leveraging unforeseen market disruptions.The core principle lies in prioritizing liquidity, scalability, and compounding effects, while mitigating lifestyle inflation that erodes wealth-building potential. Below, a structured framework outlines how to assess, reallocate, and deploy funds across three risk tiers—conservative, moderate, and aggressive—while maintaining financial resilience.
Tiered Allocation Framework: Balancing Stability and Speculative Growth
A systematic approach to fund allocation begins with categorizing expenses and investments into three risk-based tiers, each with distinct objectives and time horizons. The framework ensures that high-reward opportunities are pursued without compromising core financial stability.Context:
This tiered system prevents emotional decision-making by assigning clear roles to different asset classes. For example, emergency funds and essential expenses remain untouched, while discretionary spending (e.g., dining, subscriptions) is redirected toward assets with asymmetric upside potential—where external factors (e.g., policy changes, technological shifts, or market sentiment) amplify returns with minimal effort.
| Tier |
Risk Level |
Primary Objective |
Example Allocations |
Fortune-Driven Adjustments |
|---|
| Tier 1: Stability Core |
Low Risk |
Preserve capital, cover essentials, and ensure liquidity. |
- Emergency fund (3–6 months of expenses)
- Essential utilities, housing, healthcare
- High-yield savings accounts (HYSA) or short-term Treasury bonds
|
No reallocation; acts as a buffer for Tier 2 and Tier 3 investments.
|
| Tier 2: Growth Foundation |
Moderate Risk |
Generate steady income and long-term appreciation with controlled volatility. |
- Index funds (S&P 500, ETFs)
- Dividend-paying stocks or REITs
- Retirement accounts (401(k), IRA)
- Passive real estate (rental properties, crowdfunding)
|
Redirect 10–20% of discretionary funds (e.g., entertainment, travel) toward high-dividend REITs or blue-chip stocks with strong buyback programs. Example: Allocating $200/month from dining out to a REIT with a 5% yield compounds to ~$36,000 over 10 years.
|
| Tier 3: Fortune Accelerators |
High Risk |
Capitalize on external luck factors (market cycles, innovation, policy shifts) with potential for outsized returns. |
- Speculative assets (cryptocurrencies, meme stocks, niche IPOs)
- Leveraged real estate (fix-and-flip, short-term rentals)
- Early-stage startups or venture capital (via platforms like AngelList)
- Commodities (gold, silver, or agricultural futures)
|
Allocate 5–15% of discretionary income (e.g., subscriptions, hobbies) to high-conviction bets with clear exit strategies. Example: Reallocating $150/month from Netflix to Bitcoin during bull markets (2020–2021) yielded a 10x return in 18 months for disciplined investors.
|
The percentage allocations in Tier 2 and Tier 3 should scale with income growth and risk tolerance. For instance, a high-earner with a stable job may allocate 30% to Tier 3, while a freelancer might cap it at 10% to avoid liquidity crises.
Step-by-Step Procedure for Reallocating Discretionary Funds
Discretionary spending—often overlooked as "lifestyle expenses"—represents untapped capital for fortune-building. The following method ensures that every dollar spent on non-essentials contributes to wealth accumulation without sacrificing quality of life.Context:
The goal is to replace consumption with investment while maintaining psychological satisfaction. For example, replacing a $500/month gym membership with a fractional ownership in a boutique fitness studio (which generates rental income) achieves both health and financial objectives.
-
Audit Discretionary Spending
Track all non-essential expenses for 3 months using budgeting tools (e.g., YNAB, Mint). Categorize by:- Recurring (subscriptions, dining, entertainment)
- Impulse (online shopping, hobbies)
- Lifestyle inflation (upgrading cars, vacations)
Example: A $1,200/month discretionary budget may reveal $600 on eating out, $300 on streaming, and $200 on impulse purchases.
-
Identify High-Impact Replacement Assets
For each spending category, assign a fortune-driven alternative that:- Generates passive income or appreciation.
- Aligns with personal interests (e.g., wine enthusiasts investing in wine funds).
- Leverages external trends (e.g., AI tools, renewable energy stocks).
Example:| Expense Category |
Monthly Cost |
Fortune-Driven Replacement |
Projected 10-Year Return (Assuming 15% Annual Growth) |
|---|
| Dining Out ($600) |
$600 |
Dividend-paying restaurant REIT (e.g., Restaurant Brands International) |
$120,000 (including dividends) |
| Subscriptions ($300) |
$300 |
Fractional ownership in a co-working space (e.g., WeWork shares or peer-to-peer real estate) |
$60,000 (rental income + appreciation) |
| Impulse Purchases ($200) |
$200 |
Micro-investing in crypto via dollar-cost averaging (e.g., Ethereum, Solana) |
$40,000–$200,000 (volatile but high-upside) |
-
Implement a Phased Reallocation
Shift funds incrementally to avoid lifestyle shock:- Month 1: Redirect 25% of discretionary funds.
- Month 3: Increase to 50% after assessing comfort.
- Month 6: Optimize based on performance data.
Tool Suggestion: Automate transfers via apps like Qapital or Chime to enforce discipline.
-
Monitor and Rebalance Quarterly
Adjust allocations based on:-
The pursuit of long-term prosperity often hinges on leveraging technology to transform raw financial data into actionable insights. Modern budgeting tools extend beyond traditional expense tracking by incorporating predictive analytics, speculative asset monitoring, and opportunity-cost evaluations—key components for individuals aiming to align their finances with fortune-adjacent strategies. These technologies automate complex calculations, flag high-reward opportunities, and visualize patterns that correlate with external economic or "luck-driven" events. Below is a structured exploration of digital tools, customizable spreadsheets, AI-driven assistants, and data visualization techniques tailored for fortune-oriented financial management.
A curated selection of software and applications can streamline the monitoring of speculative assets, side hustles, and unpredictable income streams. These tools often integrate with banking APIs, market data feeds, and third-party platforms to provide real-time or near-real-time financial intelligence.
-
Investment Portfolio Analyzers
Platforms such as Portfolio Visualizer, YCharts, and Morningstar Direct specialize in tracking speculative assets, including cryptocurrencies, meme stocks, and alternative investments. Features include:- Performance benchmarking against traditional indices (e.g., S&P 500 vs. Dogecoin).
- Risk-adjusted return metrics (e.g., Sharpe ratio, Sortino ratio) tailored for high-volatility assets.
- Automated tax-lot optimization for capital gains minimization.
Example: A user tracking a portfolio of 60% Bitcoin and 40% NFTs can set custom alerts for 20% price deviations or liquidity events (e.g., OpenSea sales volume spikes).
-
Opportunity Cost Calculators
Tools like Tiller Money (Google Sheets integration) or Personal Capital quantify the trade-offs between side hustles and traditional income. Key functionalities include:- Hourly rate comparisons (e.g., freelance gigs vs. salaried work after taxes and benefits).
- Projected net income scenarios accounting for variable expenses (e.g., equipment costs for a side hustle).
- Integration with time-tracking apps (e.g., Toggl) to correlate effort with revenue.
Example: A graphic designer earning $30/hour at a 9-to-5 job may find a side hustle paying $50/hour but requiring 20% of their time—resulting in a net opportunity cost of $600/month after accounting for overhead.
-
Luck-Based Expense Categorizers
Customizable apps like YNAB (You Need A Budget) or Mint can be adapted to label expenses as "fortune-building," "fortune-neutral," or "fortune-draining." This categorization helps users:- Prioritize spending on assets with compounding potential (e.g., education, tools for a side hustle).
- Identify recurring "luck-driven" income streams (e.g., seasonal bonuses, referral commissions).
- Set rules to auto-categorize transactions (e.g., "Any spending on domain registrations = fortune-building").
Example: A musician categorizing guitar lessons as "fortune-building" and concert tickets as "fortune-neutral" ensures alignment with long-term skill development.
Customizable Spreadsheet Template for Predictable and Unpredictable Income Streams
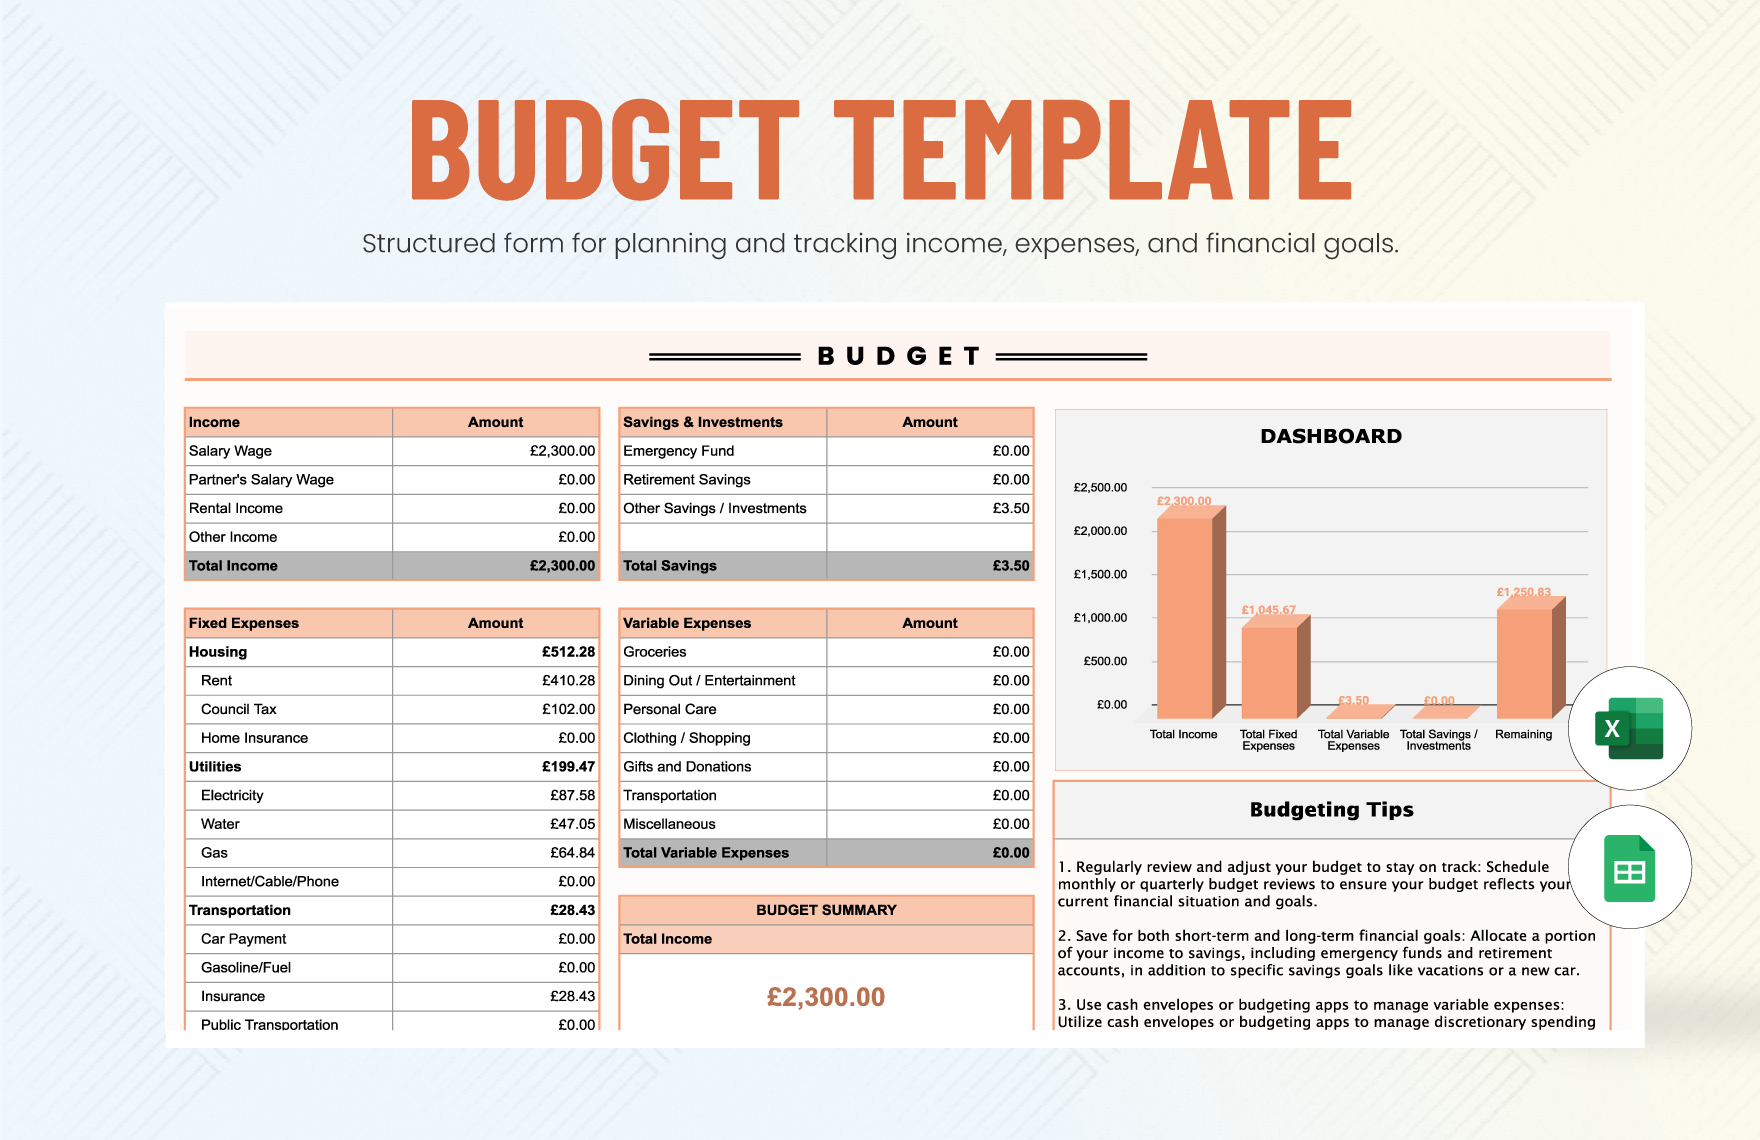
A well-structured spreadsheet can serve as a dynamic dashboard for tracking both fixed expenses and variable "luck-driven" income. Below is a template design with columns and formulas optimized for fortune-seeking budgeting.
-
Template Structure
The spreadsheet consists of four primary tabs:- Dashboard: High-level overview with visualizations (charts/graphs).
- Fixed Expenses: Recurring costs (rent, utilities, subscriptions).
- Variable Income: Unpredictable streams (gigs, bonuses, arbitrage profits).
- Fortune Metrics: Custom KPIs (e.g., "Luck Multiplier" = Variable Income / Fixed Expenses).
-
Key Columns and Formulas
-
Fixed Expenses Tab:
| Category |
Monthly Cost |
Priority (1-5) |
Formula for % of Total |
|---|
| Rent |
=SUM(Sheet2!B2:B100) |
5 |
=B2/SUM(Sheet2!B:B) |
| Subscriptions |
=SUM(Sheet2!C2:C100) |
3 |
=C2/SUM(Sheet2!B:C) |
Note: Priority columns help allocate cuts during lean periods (e.g., reduce Priority 1-2 first).
-
Variable Income Tab:
| Source |
Amount |
Frequency |
Luck Factor (1-10) |
Formula for Weighted Value |
|---|
| Freelance Gigs |
=SUM(Sheet3!A2:A100) |
Monthly |
8 |
=B2*D2 |
| Seasonal Bonuses |
=SUM(Sheet3!B2:B100) |
Quarterly |
6 |
=B3*D3 |
The Luck Factor adjusts for volatility (e.g., a one-time arbitrage profit may score 10, while a predictable referral bonus scores 4).
-
Fortune Metrics Tab:
- Net Luck Score = (Weighted Variable Income) – (Fixed Expenses).
- Luck Multiplier = Net Luck Score / Fixed Expenses.
- Opportunity Cost Ratio = (Time Spent on Side Hustles) / (Revenue Generated).
Example: A Net Luck Score of $1,200 with $3,000 in fixed expenses yields a Luck Multiplier of 0.4 (indicating room for growth).
-
Automation Features
Use Google Sheets or Excel macros to:- Auto-populate transaction data from bank feeds (via Google Finance or Power Query).
- Trigger conditional formatting for cells where Luck Factor < 3 (flagging "low-luck" income).
- Generate monthly "Fortune Reports" with trends (e.g., "Variable income increased 30% YoY during Q4").
AI-powered tools can analyze spending patterns, market anomalies, and user behavior to identify arbitrage, limited-time deals, or high-probability opportunities. Below are key features and use cases for integrating AI into budgeting.
-
Core Features of AI Assistants
Mastering the art of fortune-adjacent budgeting requires more than passive adherence to conventional savings plans—it demands a proactive mindset that embraces volatility as a catalyst for growth. By integrating structured frameworks with adaptive risk management, individuals can position themselves to capitalize on external opportunities while safeguarding their financial foundations. The key lies in striking the delicate balance between discipline and flexibility, ensuring that every dollar spent or saved aligns with both immediate needs and long-term potential. As economic landscapes evolve, so too must budgeting strategies, evolving from rigid constraints into agile systems that harness the unpredictable yet rewarding forces of luck and timing.
|
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of ir.msu.ac.zw.